...
BASIN RESEARCH

Tax questions, supported answers

A research workspace that answers federal tax questions from applicable authority and keeps the support in view.
Basin Research Hale & Marsh CPAs
Interpreting the research question
Searching primary authorities
Checking current-year amounts
Preparing the research summary
Research Result
✓ 2025 amounts confirmed Review required
Direct Answer

For tax years beginning in 2025, the Section 179 expensing limit is $1,250,000. The limit is reduced dollar for dollar once qualifying property placed in service during the year exceeds $3,130,000.

Show full analysis
Applicable Rule

IRC §199A(b)(3)(B) and §199A(d)(3) phase in the wage and basis limitation and specified service trade or business exclusion ratably over the phase-in range.

Analysis

Within the range, the disallowed portion equals the excess of taxable income over the threshold divided by $100,000.

Practical Implication

Joint filers near the threshold may benefit from timing deductions to keep taxable income inside or below the phase-in range.

Outstanding Facts

Taxable income before the deduction, business classification, W-2 wages and adjusted basis of qualified property.

Cited Authorities
Internal Revenue Code §199A(b)(3), Phase-in of limitation Primary · Current through 2025
If taxable income exceeds the threshold but remains within the applicable phase-in range, the limitation applies ratably.
Treasury Regulation §1.199A-1(d) Primary · Current through 2025
Provides rules for applying the qualified business income deduction and taxable income limitations.
Revenue Procedure 2024-40 Primary authority
Provides inflation-adjusted threshold and phase-in amounts for the 2025 tax year.

Demonstration with predefined responses. Not connected to the live research service.

THE RESEARCH WORKFLOW

Question to reviewed answer

Every question moves through the same steps, from identifying authority to saving the reviewed answer. The record shows how the conclusion was reached and what supports it.
Ask a research question
Pose the question in professional terms, with client facts attached.
Identify applicable authority
The system locates the statutes, regulations, and rulings that govern the issue.
Apply tax-year and jurisdiction context
Authority is filtered to the tax year and jurisdiction in scope.
Generate a structured answer
The answer is organized as a conclusion with its supporting analysis.
Display traceable citations
Each point links to the authority behind it, inspectable in context.
Flag judgment and review areas
Facts that require professional judgment are flagged for the reviewer.
Save the work in a private workspace
The full research record stays in a workspace scoped to your team
TRACEABLE CITATIONS

See the authority behind every answer
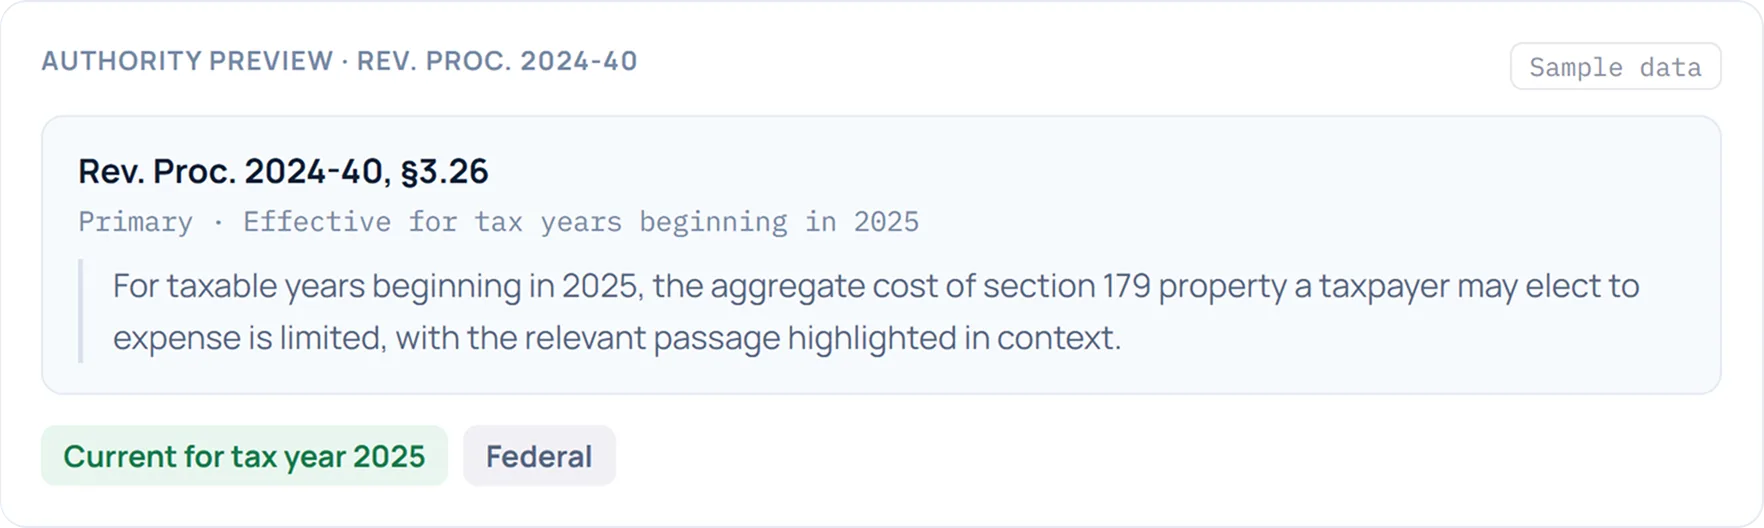
Each citation opens the underlying authority, scoped to the tax year you are working in. Where the answer depends on facts or judgment, the workspace flags it for review.
Authority preview of Rev. Proc. 2024-40, §3.26, a federal source current for tax year 2025
Try Basin Research on your next question

Enterprise: Enterprise & Institutions

For large organizations and institutions with specialized requirements, this plan offers customizable solutions. Contact us for options like multiple API keys, priority support, redistribution rights, or unlimited data access. Example use cases include:

Scale: Business / Internal Use

Built for organizations leveraging the platform for internal operations, this tier supports data-driven teams and professionals. Common applications include:

Growth: Personal & Startups

Designed for innovators, individual developers, and university researchers, this plan supports small-scale projects and early-stage experimentation. Typical scenarios include:

Explorer:

For testing purposes.
Seraphinite AcceleratorOptimized by Seraphinite Accelerator
Turns on site high speed to be attractive for people and search engines.