Skip to content

Tax questions, supported answers
- Connect and process financial information
- Review exceptions and reconcile activity
- Prepare controlled, client-ready reports
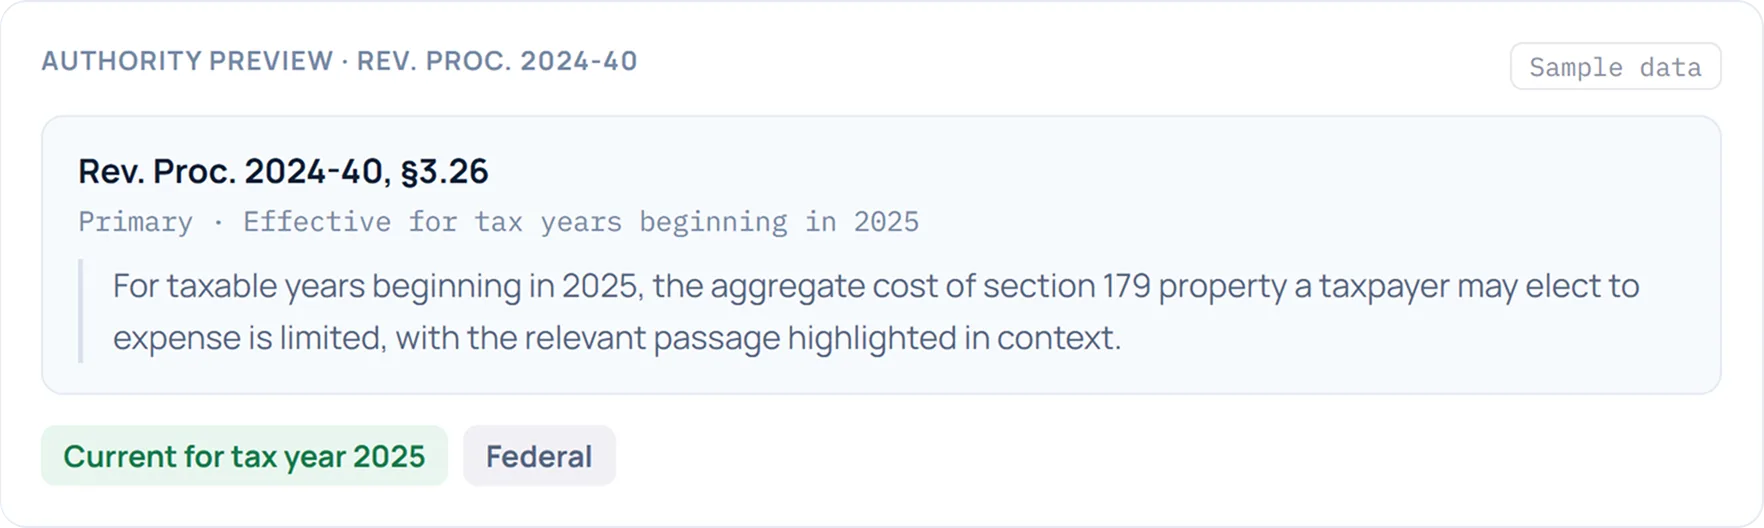
For tax years beginning in 2025, the Section 179 expensing limit is $1,250,000. The limit is reduced dollar for dollar once qualifying property placed in service during the year exceeds $3,130,000.
Show full analysisIRC §199A(b)(3)(B) and §199A(d)(3) phase in the wage and basis limitation and specified service trade or business exclusion ratably over the phase-in range.
Within the range, the disallowed portion equals the excess of taxable income over the threshold divided by $100,000.
Joint filers near the threshold may benefit from timing deductions to keep taxable income inside or below the phase-in range.
Taxable income before the deduction, business classification, W-2 wages and adjusted basis of qualified property.
If taxable income exceeds the threshold but remains within the applicable phase-in range, the limitation applies ratably.
Provides rules for applying the qualified business income deduction and taxable income limitations.
Provides inflation-adjusted threshold and phase-in amounts for the 2025 tax year.
Demonstration with predefined responses. Not connected to the live research service.
Question to reviewed answer
Ask a research question
Identify applicable authority
Apply tax-year and jurisdiction context
Generate a structured answer
Display traceable citations
Flag judgment and review areas
Save the work in a private workspace
TRACEABLE CITATIONS
See the authority behind every answer